
Selling BTC to fund a down payment can trigger a capital gains bill before you even close.
Pledging it as collateral isn't a sale, so there's no taxable event.
Keep your upside. Start at https://t.co/u4DrfJgWnJ ₿
Milo
Crypto-backed mortgages and loans from a licensed direct lender with over $250M originated
3.8/ 5
Our score
Good
Products
Crypto-backed loans
Max loan-to-value
100%
Available in
United States
KYC required
Yes
What is Milo?
Milo is a licensed financial technology company and direct mortgage lender that enables digital asset holders to borrow against their cryptocurrency. Instead of liquidating positions to buy real estate or access cash, borrowers pledge Bitcoin, Ethereum, or XRP as collateral, originating more than $250 million across its loan products.
Company and leadership
Milo was founded in 2018 by Chief Executive Officer Josip Rupena, a former financial advisor at Morgan Stanley. The company is headquartered in Miami, Florida, and operates an additional office in Colombia. Milo has raised $24 million in venture funding, backed by institutional fintech investors including M13, which led its $17 million Series A in March 2022, alongside QED Investors and MetaProp.
How crypto financing works
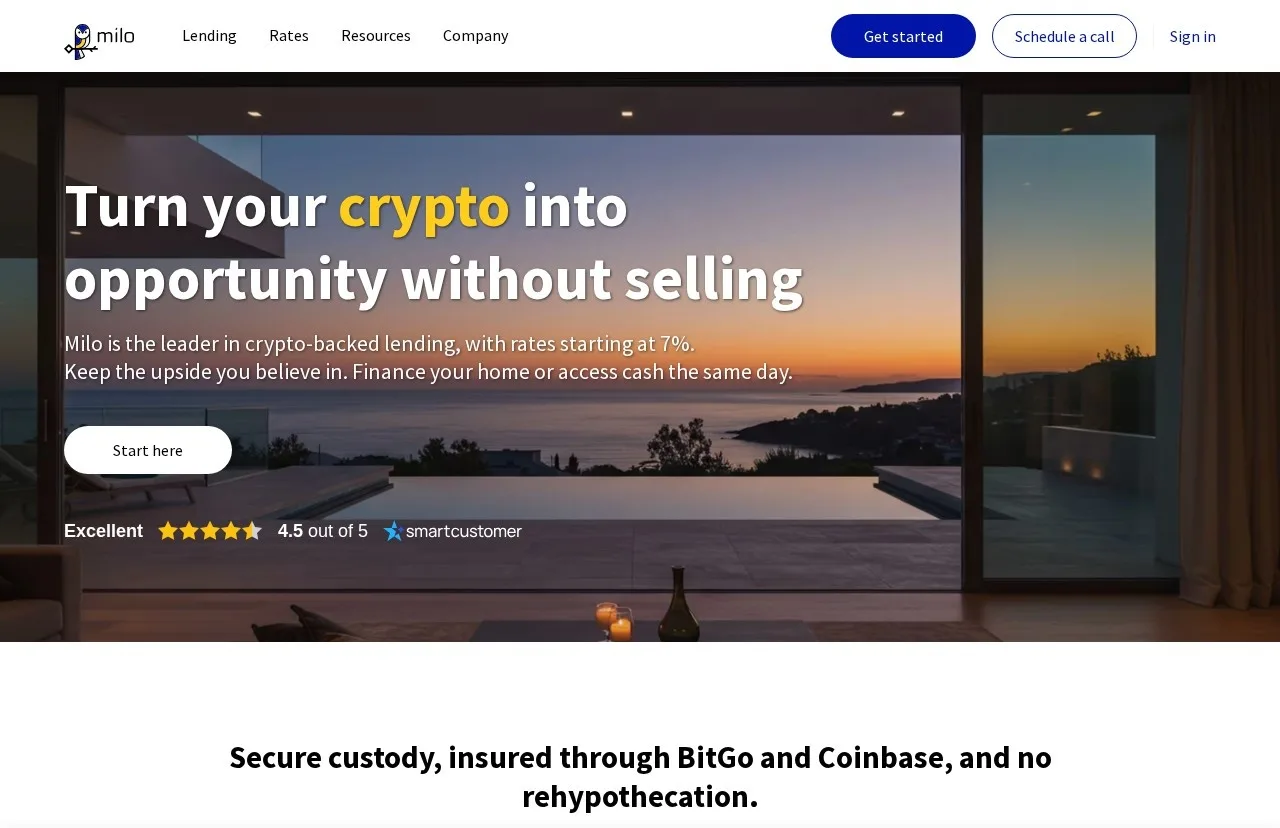
Borrowers can take out mortgages or cash loans without triggering capital gains taxes from selling assets. For crypto-backed mortgages, Milo lets clients finance up to 100% of a home purchase using pledged collateral. It also provides a self-custody mortgage structure, where digital assets remain in the borrower's private wallet to serve as qualifying reserve assets alongside a fiat down payment, avoiding margin calls. When collateral is transferred for direct lending, assets are held with qualified U.S. institutional custodians BitGo and Coinbase. Milo maintains a strict no-rehypothecation policy, meaning pledged crypto is never lent out or traded.
Fees and loan terms
Mortgage rates start from 7%. Standalone crypto-backed cash loans feature an annual percentage rate starting at 10.75%, accompanied by a 2% origination fee. In self-custody reserve mortgage structures, the minimum loan size is $200,000. Cash loan applications can provide liquidity within 24 hours.
Availability and compliance
Milo operates as a regulated direct lender holding licenses across more than 10 U.S. states. Full Know Your Customer identity verification is mandatory for all applicants, including government-issued identification checks, standard property underwriting, and cryptographic confirmation of pledged asset ownership. The firm undergoes quarterly audits.
Risks and considerations
Borrowers using standard custodial loan products face collateral liquidation risk if cryptocurrency prices decline significantly relative to the loan balance. Even though assets are stored with BitGo and Coinbase without rehypothecation, borrowers take on institutional counterparty risk with custodial partners during the term of a loan.
Founders
Josip RupenaFounder and CEO
Former financial advisor at Morgan Stanley.
Best for:Crypto holders buying U.S. real estateBorrowers avoiding capital gains taxesBitcoin holders wanting self-custodial reserves
Pros and cons
Pros
- Over $250 million originated across digital mortgage and cash lending products
- Pledged collateral is held without rehypothecation at Coinbase and BitGo
- Self-custody mortgage option removes the threat of margin calls
- Licensed direct mortgage lender holding licenses in 10+ U.S. states
Cons
- Loan APR starts at 10.75% alongside a 2% origination fee
- Mandatory identity verification and standard mortgage underwriting on all files
- Self-custody reserve mortgages require a minimum loan balance of $200,000
- Custodial loans face margin liquidation risk if crypto asset prices drop
Our review
3.8/5
Good
Milo offers compliant crypto-backed mortgages and loans with qualified custody and no rehypothecation, but borrowing costs start above traditional mortgage rates and require full identity verification.
Milo bridges traditional real estate lending and digital assets from its headquarters in Miami, Florida. Founded in 2018 by Josip Rupena, a former financial advisor at Morgan Stanley, the firm has originated over $250 million across its loan products, including more than $100 million in crypto mortgages. It backs its operations with $24 million in institutional venture funding from firms such as M13 and QED Investors.
Borrowers can access liquidity through three distinct products: standard crypto-backed mortgages, self-custody mortgages, and general crypto loans. Collateral options center on Bitcoin and Ethereum, with XRP supported on loan products. For home purchases, Milo allows borrowers to finance up to 100% of the purchase price by pledging digital assets. Alternatively, its self-custody mortgage lets clients hold crypto in their own wallets as qualifying reserves alongside a fiat down payment, avoiding margin calls for loans starting at $200,000.
Risk management differs significantly from failed centralized earn platforms. Milo avoids rehypothecation entirely, holding deposited assets with regulated qualified custodians Coinbase and BitGo. The company is an NMLS-licensed direct lender across more than 10 U.S. states and undergoes quarterly audits. These safeguards prevent yield-generation risks common in the crypto credit space, though all applicants must complete comprehensive KYC verification and standard mortgage underwriting.
The primary trade-off rests on borrowing costs. Crypto loan rates carry an APR starting at 10.75% alongside a 2% origination fee, while general starting rates begin at 7%. Several centralized crypto lenders offer lower starting entry points below 10%, though often with differing custody setups. Milo suits high-net-worth crypto holders who want to acquire property or unlock liquidity without triggering taxable capital gains, but borrowers needing low-cost leverage or unverified borrowing should look elsewhere.
Sources (1)
Specs
| KYC required ⓘ | Yes · unverified |
|---|---|
| Products | Crypto-backed loans |
| Max loan-to-value | 100% · unverified |
| Loan APR from | 7% · unverified |
| Supported assets | 3 · unverified |
| Available in | United States · unverified |
| Insurance | Custody insurance via BitGo and Coinbase · unverified |
| Licenses & registrations | Licensed mortgage lender in 10+ U.S. states, NMLS registered · unverified |
| Fixed terms | Yes · unverified |
Not disclosed by the provider: Highest advertised APY, Proof of reserves, Flexible (withdraw any time), Auto-compounding.
Data from the provider's website and public sources. Fees and availability change; confirm on the official site before you sign up.
Key features
Crypto-backed mortgages
Finance up to 100% of a home purchase using Bitcoin or Ethereum as collateral without selling assets.
Self-custody reserve option
Keep crypto in your private wallet as qualifying reserves for a minimum loan amount of $200,000 to eliminate margin calls.
Crypto liquidity loans
Access fiat liquidity within 24 hours against crypto collateral with APRs starting at 10.75% plus a 2% origination fee.
Institutional custody
Collateral is held by qualified custodians BitGo and Coinbase with zero rehypothecation.
Multi-asset collateral
Pledge major digital assets including Bitcoin, Ethereum, and XRP depending on the loan structure.
Inside Milo
Crypto-backed mortgage
Finances up to 100% of a home purchase using Bitcoin or Ethereum as pledged collateral without selling assets.
Self-custody mortgage
Enables borrowers to retain their crypto in personal custody as reserve assets for mortgage approval while avoiding margin calls.
Crypto-backed loan
Provides cash liquidity within 24 hours against Bitcoin, Ethereum, or XRP collateral.
Milo screenshots
What users say about Milo
User feedback for Milo is currently limited, consisting primarily of passing corporate discussions and team disclosures rather than organic customer reviews. There are insufficient user experiences to establish defined positive or negative themes.
Based on 5 Reddit posts and comments from the last 12 months, checked Oct 20, 2026. These are posts by users on other sites, not reviews submitted on CryptoReview.
User reviews
No user reviews yet. Have you used Milo? Share your experience below.
Funding and investors
$24MTotal raised
1Round
3Investors
-
Series A Mar 2022 $17MSource
FAQ
Who founded Milo?
Josip Rupena, a former Morgan Stanley financial advisor, founded Milo in 2018 in Miami, Florida.
What fees and interest rates does Milo charge?
Rates start at 7%, while crypto-backed cash loans carry an APR from 10.75% alongside a 2% origination fee.
Where is Milo available and is KYC required?
Milo operates as a licensed lender in more than 10 U.S. states and serves international clients. Every borrower must complete full KYC identity verification and asset verification.
How does Milo secure pledged crypto collateral?
Pledged collateral is held with qualified custodians Coinbase and BitGo without rehypothecation, and the company undergoes quarterly financial audits.
Which cryptocurrencies can be used for Milo loans?
Milo supports Bitcoin and Ethereum for crypto mortgages, while crypto cash loans accept Bitcoin, Ethereum, and XRP.
How does a Milo self-custody mortgage work?
Borrowers retain their crypto in personal self-custody wallets as qualifying financial reserves alongside a fiat down payment, which eliminates margin calls on loans of at least $200,000.
Latest from Milo on X
$100M+ in crypto-backed mortgages, originated by a licensed lender. Every one of those borrowers kept their BTC or ETH and still got the keys.
Your stack can do more than sit there. https://t.co/u4DrfJgWnJ 🏠 #CryptoMortgage
Your stack can do more than sit there. https://t.co/u4DrfJgWnJ 🏠 #CryptoMortgage
Crypto holders who already own a home: looking back, would you rather have sold to fund the down payment, or kept your stack and pledged it?
Tell us below 👇 #HomeOwnership
Tell us below 👇 #HomeOwnership
Myth: a crypto mortgage means you have to pledge your crypto.
At Milo, collateral is optional. Choose to post BTC or ETH and you can get 100% financing, without selling for a down payment.
Questions? DM us 🔑
At Milo, collateral is optional. Choose to post BTC or ETH and you can get 100% financing, without selling for a down payment.
Questions? DM us 🔑
Jan 1934: the US moved the official gold price from $20.67 to $35 overnight. A 41% dollar devaluation, by decree.
Bitcoin's supply can't be changed by decree.
Keep your BTC. Pledge it for a home: https://t.co/u4DrfJgWnJ 🏠
Bitcoin's supply can't be changed by decree.
Keep your BTC. Pledge it for a home: https://t.co/u4DrfJgWnJ 🏠
Recent public posts from @MiloCredit, shown as published. Not reviewed or endorsed by CryptoReview.
Alternatives to Milo
Gibraltar-licensed private bank offering interest-bearing USD accounts paid daily in Bitcoin
KYC requiredSavings / earn · Crypto-backed loansUnited Kingdom · GlobalFlexible (withdraw any time)
Blockchain lending platform originating over $30B in loans with crypto-backed credit at 50% LTV
KYC requiredSavings / earn · Crypto-backed loansUnited StatesHighest advertised APY 9%
Bitcoin-backed lending platform operating since 2018, with $11.5B in lifetime loans funded
KYC requiredCrypto-backed loansGlobal · Canada +6Proof of reserves
Crypto earning suite with on-chain staking and MiCA regulation covering 30 European markets
KYC requiredSavings / earn · Staking +1Europe (EEA) · United States +1Proof of reserves
Crypto-backed loans in USD or USDC with segregated custody at Anchorage Digital
KYC requiredCrypto-backed loansUnited StatesFlexible (withdraw any time)
Custodial yield and staking suite from an exchange with over 300 million registered accounts
KYC requiredSavings / earn · Fixed-term deposits +2Proof of reservesFlexible (withdraw any time)